

Blog
MENA vs. GCC vs. Arab World: Key Differences Every Trader Must Know in 2026
In over four decades of navigating international trade, I’ve seen how misunderstanding regional groupings can cost businesses dearly. Picture this: A supplier quotes prices assuming a unified “Middle East” market, only to face wildly different tariffs, regulations, and buyer behaviors across borders. According to World Bank data, the Middle East and North Africa (MENA) region accounts for about 6% of the global population but holds 60% of oil reserves and 45% of natural gas—yet trade flows vary dramatically within it.
These distinctions aren’t just academic. They directly impact sourcing decisions, supply chain risks, and partnership opportunities in wholesale and export markets.
What Is the MENA Region?
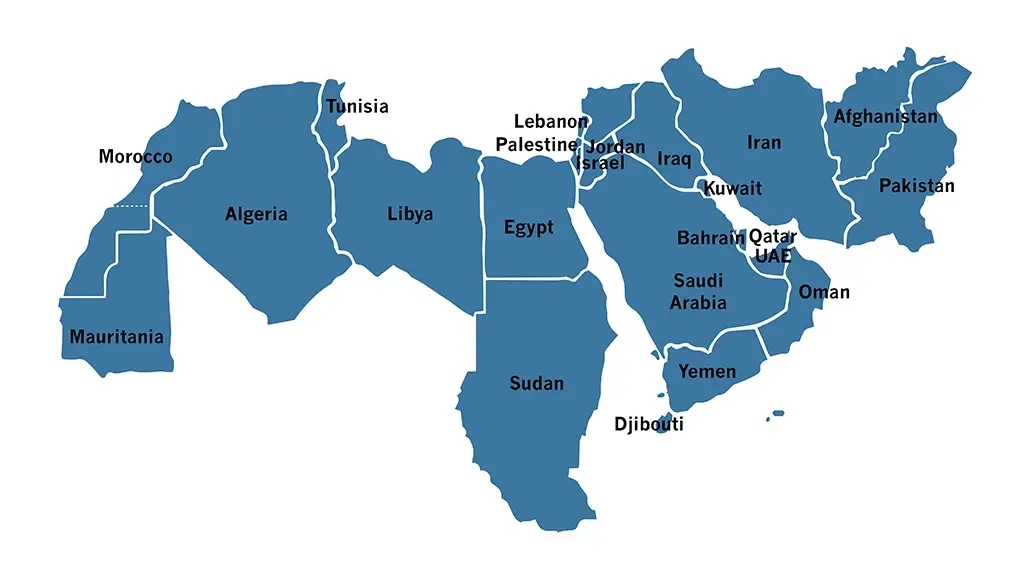
The MENA acronym stands for Middle East and North Africa. It’s a geographic and economic grouping used by organizations like the World Bank, IMF, and UN.
Definitions vary slightly, but core countries include:
- Algeria
- Bahrain
- Egypt
- Iraq
- Jordan
- Kuwait
- Lebanon
- Libya
- Morocco
- Oman
- Qatar
- Saudi Arabia
- Tunisia
- United Arab Emirates
- Yemen
Often added: Iran, Djibouti, Syria, Sudan, and sometimes Israel or Palestine.
MENA spans diverse economies—from oil-rich powerhouses to import-dependent nations. It covers arid climates, rapid urbanization, and young populations driving demand in construction, energy, and consumer goods.
Why it matters for trade: MENA represents a massive import market, with non-oil trade growing steadily. However, political instability in parts like Syria or Libya contrasts with stable hubs in the Gulf.
MENA Region
Defining the GCC: The Gulf Cooperation Council
The GCC is a political and economic alliance of six Arab states bordering the Persian Gulf:
- Bahrain
- Kuwait
- Oman
- Qatar
- Saudi Arabia
- United Arab Emirates
Established in 1981, the GCC promotes integration through a customs union, common market, and coordinated policies. Members share monarchies, oil-driven wealth, and strategic goals like diversification under visions such as Saudi Vision 2030.
Key traits:
- High GDP per capita (often exceeding $50,000 in Qatar and UAE).
- Surplus budgets from hydrocarbons.
- Heavy investment in non-oil sectors like logistics and tech.
For traders: GCC countries offer seamless intra-regional movement, low internal tariffs, and massive infrastructure projects. They dominate MENA’s export power but import heavily in machinery, food, and raw materials.
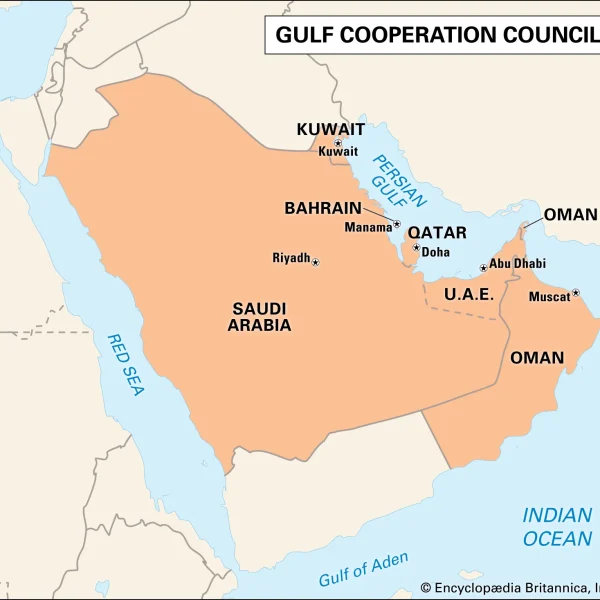
GCC
The Arab World: League of Arab States Members
The Arab countries or Arab world refers to the 22 members of the League of Arab States, united by Arabic as the primary language and shared cultural heritage:
- Algeria
- Bahrain
- Comoros
- Djibouti
- Egypt
- Iraq
- Jordan
- Kuwait
- Lebanon
- Libya
- Mauritania
- Morocco
- Oman
- Palestine
- Qatar
- Saudi Arabia
- Somalia
- Sudan
- Syria
- Tunisia
- United Arab Emirates
- Yemen
This grouping emphasizes Pan-Arab identity, with the league coordinating on political and cultural issues since 1945.
Trade insight: Arab countries form a vast Arabic-speaking market, ideal for unified marketing in agriculture, food, or consumer products. Yet economic disparities are stark—from GCC wealth to challenges in Yemen or Somalia.
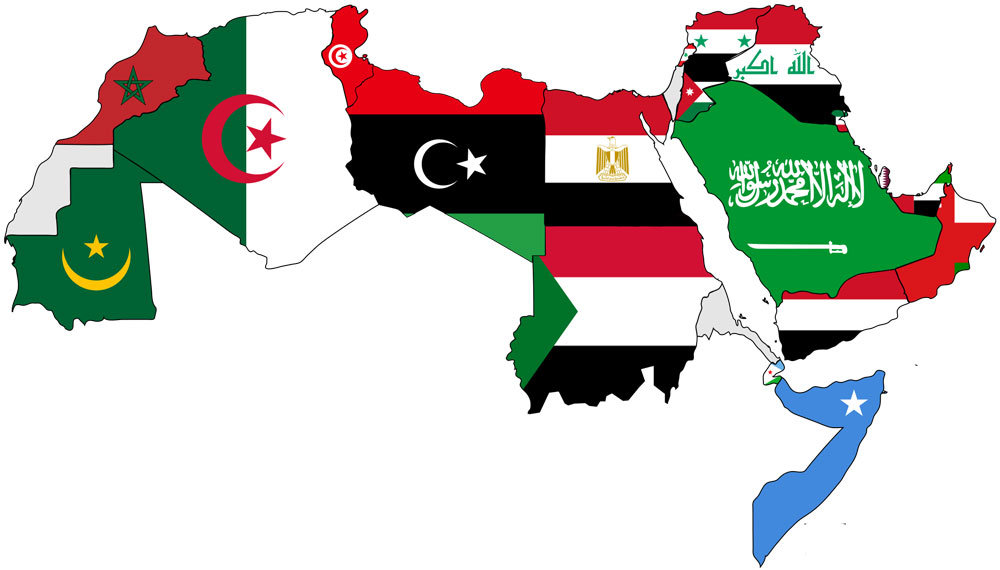
The Arab World
Key Differences: A Side-by-Side Comparison
These regions overlap significantly—the GCC is fully within both MENA and the Arab world—but differences drive real business outcomes.
| Aspect | MENA (Broader Geographic/Economic) | GCC (Gulf Alliance) | Arab Countries (Cultural/Political) |
|---|---|---|---|
| Number of Countries | 18-21 (varies by definition) | 6 | 22 |
| Core Focus | Economic analysis, development | Political/economic integration | Cultural unity, Pan-Arab coordination |
| Non-Arab Inclusions | Often Iran, Israel, sometimes Turkey | None—all Arab | None—all Arabic-speaking |
| Economic Profile | Mixed: Oil exporters + importers; wide inequality | High-income, oil-dominant; diversification push | Varied: Wealthy Gulf + lower-income North Africa/Levant |
| Political Stability | Varies (conflicts in some areas) | Generally high, monarchies | Diverse systems, historical upheavals |
| Trade Advantages | Broad market access, diverse resources | Customs union, easy cross-border trade | Shared language/culture for marketing |
GCC economies outperform the wider MENA. Fitch Solutions notes GCC growth relies on stable oil and robust non-oil sectors, maintaining surpluses while North Africa faces challenges.
- GCC: Often surpluses, low debt, Vision 2030-style diversification.
- Broader MENA/Arab: Many oil importers run deficits; reliance on remittances and aid.
Case in point: UAE and Saudi Arabia lead regional investments in renewables and logistics, creating opportunities in industrial equipment and construction materials.
Political and Cultural Variations
GCC states share monarchies and Gulf-specific alliances, prioritizing stability and countering external influences.
The wider Arab world includes republics (Egypt, Tunisia) and diverse histories, from Ottoman legacies in the Levant to colonial impacts in North Africa.
Culturally:
- GCC: Cosmopolitan hubs (Dubai, Doha) with expat majorities.
- Broader regions: Stronger local dialects, varied religious practices.
These shape buyer preferences—conservative sourcing in some areas versus innovative tenders in Gulf megaprojects.
The BRICS+ Expansion & New Economic Blocs: Redefining MENA Trade (2025–2026)
In recent years, the global trade architecture has witnessed a profound shift with the expansion of the BRICS+ bloc. The inclusion of key Middle Eastern and North African heavyweights—specifically the United Arab Emirates, Saudi Arabia, and Egypt—has transformed the region from a traditional Western-aligned trade zone into a central pillar of multipolar commerce and financial diversification.
1. Strategic Shifts for MENA and GCC Powerhouses
By joining or aligning closely with BRICS+, countries like the UAE and Saudi Arabia are leveraging their geopolitical and economic heft to secure bilateral partnerships outside traditional Western-centric frameworks. For global traders, this expansion introduces crucial dynamics:
- De-Dollarization and Local Currency Trade: A primary objective for the expanded BRICS bloc is reducing reliance on the U.S. dollar in international commodities and energy settlements. Energy exporters in the GCC are increasingly open to settling oil and gas trades in local currencies (such as Chinese Yuan, UAE Dirhams, or Indian Rupees), minimizing foreign exchange risks for specific corridors.
- Alternative Financial & Settlement Systems: Initiatives like decentralized payment messaging frameworks and digital currency platforms (e.g., mBridge) are reshaping cross-border transactions. For wholesale exporters and importers, this means exploring alternative financial corridors that bypass conventional Western banking bottlenecks.
- Enhanced Supply Chain Resilience: Egypt’s integration into BRICS bridges North African manufacturing and agricultural power with Asian consumer markets, creating streamlined logistics pathways through the Suez Canal and regional industrial zones.
2. What This Means for Global Traders
Misunderstanding these modern economic blocs can leave global businesses at a competitive disadvantage. Traders operating within the MENA and GCC ecosystems must now factor in:
- Diversified Sourcing Routes: Bilateral trade agreements between BRICS members facilitate smoother customs procedures and preferential tariffs for raw materials, machinery, and agricultural goods.
- Adaptability to Multi-Currency Invoicing: Exporters dealing with Gulf or North African buyers should prepare for flexible payment terms, including local currency invoicing options that reduce transaction friction.
New Trade Corridors: IMEC, North-South Route, and MENA’s Rise as a Global Transit Hub
As global supply chains shift toward resilience and diversification, geography is no longer just about location—it is about connectivity. The wider MENA and GCC regions are rapidly cementing their status as the ultimate bridge between Asia, Europe, and Africa through transformative mega-logistics corridors.
1. The India-Middle East-Europe Economic Corridor (IMEC)
Unveiled to reshape international trade routes, the IMEC corridor directly connects India through the Arabian Gulf—specifically via the UAE and Saudi Arabia—across Jordan and Israel to Europe. For global traders and logistics operators, IMEC represents:
- Unprecedented Transit Speed: Offering a faster and more cost-effective alternative to maritime-only routes through the Suez Canal by combining shipping lanes with modern railway and road networks.
- Strategic GCC Hubs: Ports in the UAE (such as Jebel Ali) and Saudi Arabia (such as King Abdulaziz Port) act as critical transshipment anchors, linking eastern manufacturing powerhouses with western consumer markets.
2. The International North-South Transport Corridor (INSTC)
Complementing Gulf-centric initiatives, the INSTC connects South Asia and the Persian Gulf (via Iran and Caspian networks) to Russia and Northern Europe. This multi-modal network provides a vital channel for bulk goods, agricultural exports, and industrial machinery, significantly cutting transit times compared to traditional maritime routes via the Baltic or Black Seas.
3. Strategic Implications for Exporters and Importers
The institutionalization of these trade corridors transforms how businesses approach regional supply chain planning:
- Multi-Modal Sourcing: Businesses can leverage flexible logistics options—balancing maritime, rail, and road freight to mitigate transit bottlenecks.
- Investment in Logistics Real Estate: Free zones and industrial cities along these corridors (such as Saudi Arabia’s special economic zones and UAE logistics parks) offer unmatched warehousing and distribution advantages for wholesale trade.
Why These Distinctions Matter in Global Trade Today
Mislabeling a market as “MENA” when targeting GCC-specific tenders can mean missing customs benefits or regulatory alignments.
Opportunities:
- GCC focus → High-value bulk deals in energy and infrastructure.
- Wider Arab/MENA → Volume plays in agriculture and consumer goods.
Geopolitical risks differ too—GCC stability contrasts with volatility elsewhere, affecting supply chain resilience.
For deeper dives, check related insights on Unlocking Supply Chain Opportunities in Saudi Vision 2030 or Geopolitical Risks in Global Trade.
Navigating These Regions Successfully: Actionable Steps
- Map your targets precisely — Use GCC for integrated Gulf projects; expand to full MENA for diversified sourcing.
- Leverage shared strengths — Arabic language and Islamic calendar unify marketing across Arab countries.
- Mitigate risks — Prioritize GCC for stability; build contingencies for broader MENA.
- Stay data-driven — Track IMF/World Bank reports on regional shifts.
- Build local partnerships — Verified networks cut through cultural and regulatory barriers.
In wholesale trade, precision on these regions turns potential pitfalls into profitable edges.
Ready to source reliably across these markets or list products for global buyers? Join Tendify.net today—connect directly with verified traders, post RFQs, and secure deals in growing sectors like construction, energy, and agriculture. Sign up now and start building your next trade opportunity.